

Those of you who’ve been following me a while remember the article on the economics of military readiness. In it, I talked about how the most important question in arms deals isn’t “what am I buying” but “how am I going to operate it.” Now let’s go further and ask: who’s going to pay for these weapons?
The answer to this question matters. It’ll help us understand what it means when a country like Germany, for example, announces $100 billion in defense investments. Does that mean they’ve paid this money already? And is the state itself the one paying it?
This is a different topic from the defense budget, and deeper than budget topics in general, because this is about the financial engineering behind arming and defense manufacturing. In recent years there’s been a major increase in defense budgets. But the more important thing, which isn’t written about much, is the bigger change in the way weapons themselves are paid for.
What does all this mean?
In March 2025, Europe said: we’ve made a plan called Readiness 2030, and its goal is to mobilize more than 800 billion euros for defense spending. Anyone not following closely would think this is money Europe is paying directly for defense out of its budget.
But the truth is that this isn’t correct. It’s a huge number for all of Europe. So the question is: where are they going to get this money from?
Europe is simply going to borrow in order to arm itself.
There’s a program called SAFE, which stands for Security Action for Europe. Through this program, Europe is going to borrow 150 billion euros. From where? From the capital markets. How? By issuing European bonds, or EU-bonds, and then distributing this money to countries in the form of long-term loans with low interest.
This plan has actually already begun, and its goal is for Europe to buy weapons collectively. And 18 countries have requested loans worth $127 billion, and there are still more countries waiting.
Personally, I think the correct name for this should be “war bonds.” Europe, almost the richest economic bloc in the world, is borrowing in order to arm itself. And it’s created a modern model of war bonds so it can afford this arming.
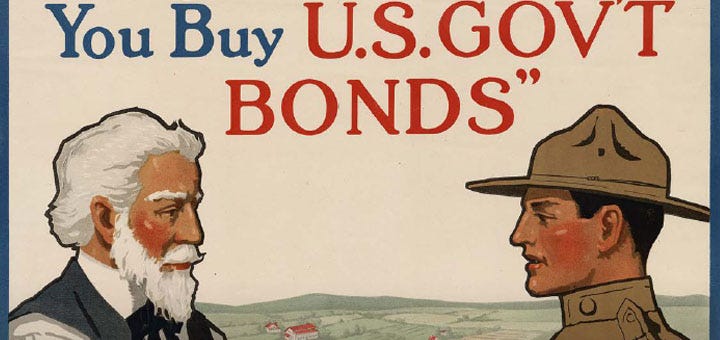
War bonds happened during the two World Wars, when America sold Liberty Bonds to citizens in order to fund the war from the people’s pockets. The difference in Europe’s version today is that it’s not selling to citizens but to the capital markets.
Even this model is not easy to implement, because there are countries opposed to this model. The most important of them are Germany and Sweden. The disagreement, simply put, is that the rich countries say: we can’t guarantee the debt all together, because as rich countries we’d be bearing the burdens of countries poorer than us.
Estonia, Poland, France, and Italy are in favor of the idea. And the matter turned into a political-economic struggle, part of which I worked on in a research paper about Eastern European countries. In it, I say a new European dilemma has appeared because of the Ukraine war. The Eastern European countries say: we’re increasing our defense spending so that companies in Germany, France, and Italy can benefit from it. And at the same time, the countries that have those companies say: why should I participate in joint defense bonds and carry a burden that isn’t mine?
Okay, so why doesn’t the European Investment Bank provide financing for defense?
For two reasons. The first is that the required number is huge. Before the war, the bank was financing defense at 1 billion euros. In 2025 it became financing at 4 billion euros. And the required number is 800 billion. You see the difference?
The second reason is the statement by the bank’s president when she said, “The European Investment Bank is not a defense ministry,” in order to respond to the political pressures trying to turn the bank into a weapons financier. And they say that financing defense has an ethical taint to it. Yes, they said that.
Now let’s come to the part I personally love, which is the entry of Venture Capital into the defense industries.
To understand the shock, you have to understand that venture capital historically financed mobile apps, software companies, and startups. But it didn’t go near weapons at all. It used to avoid them for ethical and investment reasons.
Now those reasons have vanished. And in 2025 alone, venture capital pumped a record number into the defense-tech companies we call defense-tech. The estimates talk about $7.7 billion directly and $29 billion indirectly. And the number of deals reached 629 deals in a single year. These numbers are huge, and they’re a big change in the logic of defense itself.
The most important example is the American company Anduril. In June 2025 it was valued at $30.5 billion. And on May 13, 2026 (just one month ago), it raised $5 billion in a single funding round, and its value reached $61 billion. Double its value in just 11 months.
To picture the number: this company is 9 years old, and its value has come to approach the giant arms companies that are a century old.
And who’s financing this?
Various funds, like the American Dynamism fund by Andreessen Horowitz, which raised $1.176 billion in January 2026 alone. And the Founders Fund, which pumped a $1 billion check into Anduril. The largest single investment in the history of defense-tech.
But the part that interests us more is that NATO itself created a venture capital fund called the NATO Innovation Fund, with 1 billion euros. The first multi-sovereign venture fund in the world. 24 countries putting their money in it. And they describe themselves as a patient investor that provides support for up to 15 years.
And here comes a pivotal concept you need to know, called the Valley of Death. It’s the deadly gap between making a working prototype of a weapon and getting a large-scale production contract. Most small companies die in this gap, which is why it’s called the Valley of Death, because the banks don’t finance them and the government hasn’t bought from them yet.
And here venture capital and Patient Capital entered in order to get companies across this valley. And this connects to what I wrote before about SMEs, because these are exactly the companies that die in the Valley of Death if no one finances them.
Okay, but all weapons come from a production line. Who finances these production lines?
In 2023 the European Union did something for the first time in its history: a tool called ASAP, which stands for Act in Support of Ammunition Production. They allocated 500 million euros from the EU budget to finance ammunition production directly. The first time the European budget paid for weapons. And they distributed it across 31 projects.
The goal was to raise artillery shell production to 2 million shells annually by the end of 2025. Why? Because Ukraine is burning through ammunition faster than the production capacity. As I said before, the battle has become between one stockpile and another. And industrial capacity is combat capacity.
But the smartest tool, in my opinion, is the one America is doing. It’s called Multi-year Procurement.
And this is simply that the military signs a contract with the company for a period reaching up to 7 years, in order to give it the confidence to build a new factory safely.
And the twist here is that these contracts made the company the one that pays the cost of building the factory out of its own pocket, and pays a penalty if it doesn’t meet the production rates. An American official said a nice line: “We make them put their skin in the game.” And this is very important in the system we’re talking about: risk-sharing, and the role of the state in making policies that regulate risk-sharing in the industry.
Alright. This is all Western talk. Let’s look at other models.
Turkey has a fund called the Defense Industry Support Fund, SSDF, in Turkish Savunma Sanayii Destekleme Fonu. It was established in 1985. The idea in it is that it’s funded from outside the regular budget. It’s funded from additional taxes on alcohol, tobacco, fuel, the lottery, and gambling games.
Its revenues in 2023 reached $3.9 billion. And this is a dedicated, independent defense fund, which finances Baykar, Aselsan, and Roketsan indirectly through the Turkish Armed Forces Foundation, TSKGV, which owns stakes in these companies.
Worth mentioning that in October 2024, the Turkish government tried to impose new taxes (on credit cards and real estate transactions) in order to boost this fund with an additional $2 billion. At that time the people got upset and the government backed down. Meaning even this financing has a political ceiling.
The Gulf has a completely different model. Not a defense fund, but sovereign wealth funds. Saudi Arabia’s Public Investment Fund, PIF, has passed $1.15 trillion. And the Emirates created a company called EDGE Group in 2019. They merged more than 25 entities into it. And its revenues in 2024 reached $4.9 billion, and it entered the SIPRI list of the top 100 arms companies at rank 37. The Gulf finances defense from oil surpluses through the sovereign funds, not from loans or taxes.
India has a third model: grants for startups. A program called iDEX, and after it ADITI, which gives grants to small emerging companies. And up to the beginning of 2025, they financed 619 startups and made 430 contracts.
And Israel turned the war into an opportunity for innovation. The number of defense-tech companies it has increased from 160 to more than 300 in a year. And they raised more than $1 billion in 2025 alone. And the state gives government guarantees of up to $60 million in order to establish defense venture capital funds. Meaning the state carries the risk off the investor so that he’ll enter.
Egypt (one of the major powers in the middle east) doesn’t have a dedicated defense fund like Turkey, for example. Nor defense bonds like Europe. There’s no defense venture capital system like Israel and India. And the financing is very weak and depends on the budget, aid, Gulf investment, and partnerships. And there’s no innovative financial tool to get the small companies out of the Valley of Death we talked about—that is, if you can even reach it in the first place.